
• Home
    • News Insight Snapshot Morning express Daily Weekly Operation report Monthly
    • Market price Database Annual report Researchpremium Focuspremium Mobile Apppremium      
  • Data & API Services
  • Consulting
  • Industry Conference
  • Company Profile Contact Us Website Guide
  • FAQ
  •     
7-day free trial Login
  • Chemicals
    Benzene Styrene Toluene Xylene Methanol DEG PP PE
  • Polyester
    PX/PTA MEG PET fiber chip PET bottle chip PFY PSF
  • Recycled fiber
    PET Flakes Re-PSF Re-PFY
  • Nylon
    CPL/PA6 AA/PA66 Nylon Fiber
  • Spandex
    PTMEG/MDI Spandex
  • Acrylic
    Acrylonitrile Acrylic Fiber
  • Cellulose
    Cotton linter/refined cotton Pulp VSF VFY Rayon yarn
  • Cotton
  • Spun Yarn
  • Textiles
  • Researchpremium
  • Focuspremium
×

Perfect storm hits polyester: who dares to stock up now?

Monica Jiang
Insight  |  Time: Nov 21 2026 2:18PM
Nov brings a brutal downturn across the polyester chain, hit by plunging crude oil prices and disappointing seasonal demand. The failed "Golden September & Silver October" peak season crushed hopes for winter fabric sales. Sharp raw material losses have flipped market sentiment deeply bearish. Downstream operators are avoiding inventory exposure, only producing for immediate rigid orders while weaving and spinning facilities roll out production cuts. The whole industry remains locked in a prolonged wait-a

The polyester industrial chain is caught in a cold wave in Nov, driven by the combined shock of cost collapse and sluggish demand. Since the start of Nov, prices have fallen across the board from crude oil down to polyester end products within just over two weeks. WTI and Brent crude oil futures plunged to $84/bbl and $92/bbl respectively, dropping more than $20/bbl from late Oct. PTA and PSF shed over 700yuan/mt, falling to roughly 6,500yuan/mt and 8,400yuan/mt. Yarns posted comparatively limited losses given their modest prior gains. Ring-spun T32 and MVS T30 fell around 150yuan/mt and 200yuan/mt.


1. Demand vacuum after failed "Golden September and Silver October"

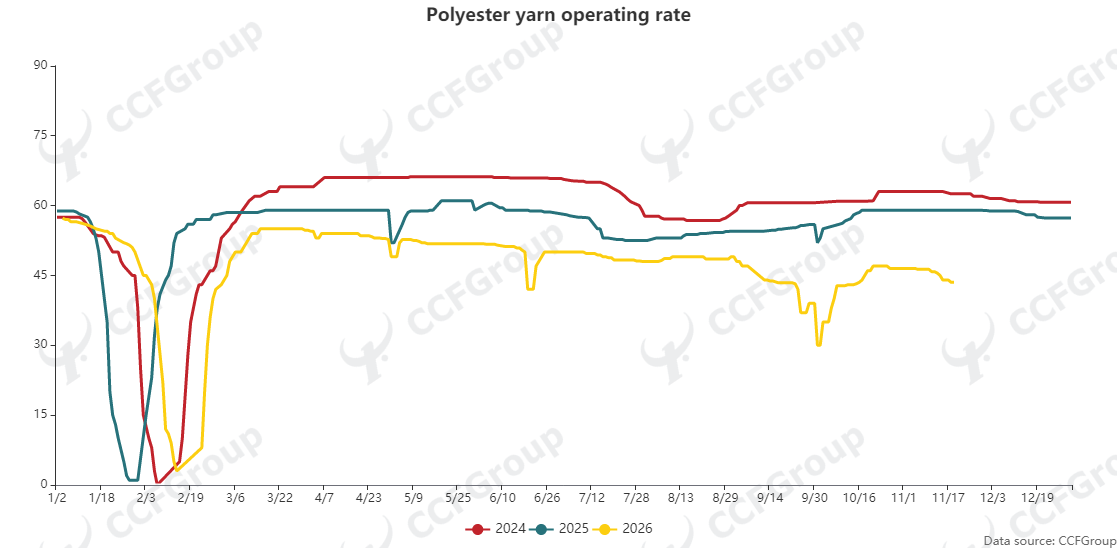
Market participants had hoped cooling temperatures in Nov would boost sales of winter fabrics, yet trading remained muted. The fizzled "Golden September and Silver October" peak season erased optimism over seasonal follow-up demand. Pessimism downstream has translated into tangible action. Production cuts and output curbs have spread across segments. Operating rates for looms, texturing and printing & dyeing facilities in Jiangsu and Zhejiang declined in tandem. Polyester yarn mills have run at low operating rates since Mar, and even MVS plants-which rarely cut production in normal times-have joined widespread output restrictions under mounting pressure.

hr_wordimg_1795241958890_85428.png


2. Sentiment shift: who dares to hold inventory?

Shutdowns and production curbs downstream, while seemingly triggered by cost headwinds, essentially stem from lost confidence in the market outlook. Macro expectations reversed after the US midterm elections, sending crude oil prices tumbling and spreading strong bearish sentiment throughout the chain. Odds of US-Iran detente have risen, with some institutions forecasting crude oil could fall to $70/bbl. Against such strong downward expectations, downstream buyers have turned highly cautious: "We will not build inventory lightly unless raw materials bottom out." Driven by the classic "buy on rises, not falls" mentality, downstream firms only fulfill rigid orders and maintain minimal inventory to guard against asset depreciation.


This downtrend compounded by off-season conditions has crippled sales, and yarn mills are under growing strain. Current production cuts are both passive defense and a risk-aversion strategy. The standoff and game between upstream and downstream players will likely persist for some time until a genuine bottom is confirmed.

[RISK DISCLAIMER] All opinions, news, analysis, prices or other information contained on this report is provided by analyst of Zhejiang Huarui Information Consulting Co., Ltd (CCFGroup) as general market commentary and does not constitute investment advice. CCFGroup will not accept liability for any loss or damage, including without limitation to, any loss of profit, which may arise directly or indirectly from use of or reliance on such information.

Related Articles

    International cotton yarn market weekly (Nov16-20, 2026)
    Rayon yarn exports drops in Oct 2026
    Rayon yarn trading keeps sluggish
    Cotton yarn prices stable
    Rayon yarn market morning express (Nov 20, 2026)
    Polyester yarn export of China drops in Oct

Researchpremium

    Substitution dynamics between virgin and recycled cotton-type PSF
    Operating performance of listed Chinese textile and apparel enterprises in H1 2026
    2025/26 Chinese cotton market fundamental analysis and outlook
    Operation analysis of China's lyocell and rayon printed & dyed fabrics
    Cotton yarn market: H1 review and H2 outlook
    Analysis of polyester demand in H1 2026 and H2 outlook
  • Address
    Huarui Center No. 1027 Jianshe 1st Road,
    Hangzhou, Zhejiang Province, China
  • Phone
    +86-571-8378 6653    +86-571-8378 6504
  • Email
    market@ccfgroup.com
Our Service
  • Home
  • Market price
  • Database
  • Research
  • Focus
  • Website Guide
  • Data & API services
  • Consulting
  • Industry conference
  • Company profile
  • Mobile app
  • FAQ
About Us


A leading provider of market intelligence, data services, and industry insights across the petrochemical, chemical fiber, and textile value chains.

© Huarui Information All Rights Reserved   Privacy Policy · Terms of Use

China ICP License: 浙B2-20110322-3
浙公网安备33010902000742号