

EO supply recovers, prompting shifts toward MEG |
|
| Michael Zhao | |
| Insight | Time: Nov 20 2026 4:24PM | |
China's EO supply has recovered, prompting some integrated producers to shift output to MEG. However, delayed restarts and uncertain imports will limit MEG supply growth in December.
East China's listed EO price fell to around 9,100 yuan/mt in early-to-mid November, ending six weeks of elevated trading on lower costs and expected supply gains.
Yangzi Petrochemical, Taixing Jinyan and Hainan Refining restarted a combined 700,000 mt/year of capacity this week, while restarts in northern Jiangsu lifted average operating rates to around 60%.
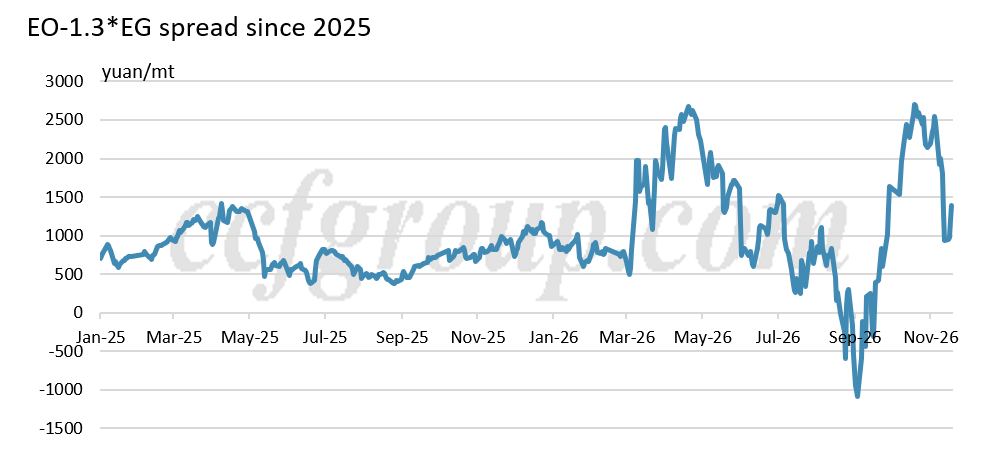
With MEG prices retreating, the EO minus 1.3 * MEG spread stands at 1,300-1,400 yuan/mt, versus earlier lows below 1,000 yuan/mt.
Zhenhai Refining, Sanjiang Petrochemical and Wuhan Petrochemical adjusted their product mix, adding about 300-400 mt/day of MEG output.
More shifts are possible. EO buyers are purchasing on a need-to basis amid high prices, and colder weather will curb superplasticizer monomer demand in northern China. Far Eastern Union Petrochemical and Northern Chemical may move more output to MEG if EO sales stay weak.
Product mix adjustments could add 20,000-30,000 mt/month of MEG, but other restarts are lagging. Shenghong Refining's 1 million mt/year plant has been delayed to around late December, and Sabic Fujian Petrochemical's new unit will contribute from mid-to-late December.
China's December MEG output is now forecast at 2.0-2.02 million mt, well below earlier expectations.
Only three MEG vessels effectively exited the Persian Gulf in November, with some cargoes diverted to other Asian markets. Some December deep-sea cargoes, including from Canada, also face delays.
Overall, December MEG availability may be tighter than previously expected.