

MEG inventory outlook reverses: can the spot basis rally further? |
|
| Michael Zhao | |
| Insight | Time: Nov 12 2026 3:57PM | |
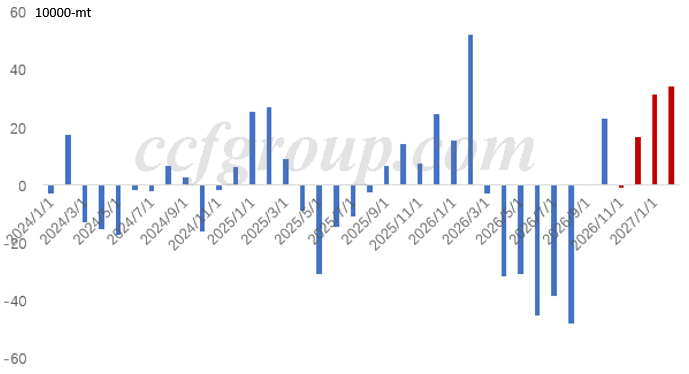
China's MEG market has shifted toward a tighter near-term balance as sustained production cuts and recovering polyester demand reduce tradable supply. The November supply-demand balance has moved from an expected inventory build to a slight drawdown, supporting a sharp rise in the spot basis.
High naphtha prices have squeezed oil-based MEG margins since October. By late October, China's ethylene-based MEG output had fallen by more than 3 kt/day from its September high. Further cuts followed in November, as Satellite Petrochemical switched its product slate and Yulong Petrochemical's 900 kt/year unit shut unexpectedly.
Non-coal-based MEG operating rates have dropped to 62-63% from around 77% in early September, a decline of about 14 percentage points in two months. Crucially, these are actual cuts that have materialized since October, not merely expected ones.
China's polyester operating rate has recovered from around 74% in early October to 78%, accelerating port withdrawals and limiting visible inventory accumulation.
Of the roughly 230 kt inventory build implied by October's balance, an estimated 60-70% sat with polyester producers. This eased their restocking needs but added little to tradable supply.
With domestic output falling and polyester demand improving, November's balance has shifted to a slight inventory draw. Vessel arrivals are expected to stay light from mid-November through early to mid-December, and most incoming cargoes are already held by polyester producers, leaving very little available for trading.
December MEG imports were previously expected to reach around 300 kt, based on vessel transit rates out of the Persian Gulf and cargoes already loading, including on the NCC Fajr. However, recent tanker attacks have increased uncertainty over shipment schedules.
The Liberian-flagged MT Fujairah Energy was reportedly struck by a projectile in the Persian Gulf on November 10, followed by a suspected attack on the Saudi-flagged NCC Fajr on November 11.
If the NCC Fajr is confirmed to have been hit and cannot reach China in December as scheduled, December imports would need to be revised down to around 250 kt. The attacks could also slow vessel transits through the strait, significantly raising uncertainty over medium-term import volumes.
Assuming imports of 250 kt, scheduled plant restarts and startups, and an average polyester operating rate of 79%, December MEG inventories are projected to build by around 160 kt. From a low starting base, however, much of this build is likely to end up as hidden inventory, with only a limited increase in visible port stocks.
Monthly MEG supply & demand balance
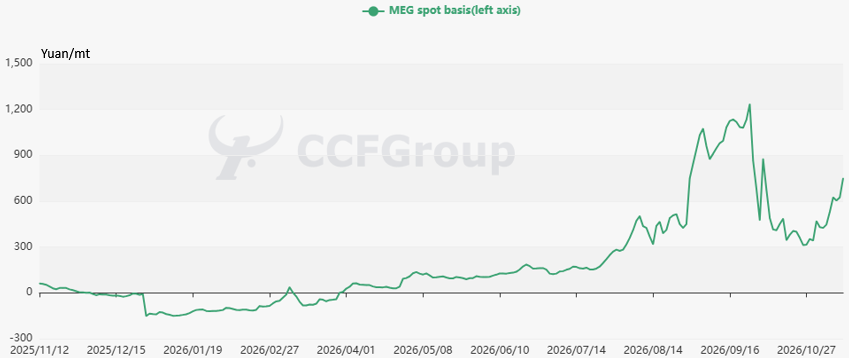
Low inventories, limited arrivals and scarce tradable cargoes have quickly shifted the forward curve into backwardation. The spot basis has risen rapidly and is now approaching the levels seen during the September contract rally.
Unlike the September rally, however, several MEG plants are scheduled to start or restart before the January contract expires. Their actual startup timing will determine the extent of further basis gains and the direction of the January-May futures spread.
Meanwhile, year-end contract negotiations and polyester producers' restocking needs, as run rates recover, could lend additional support to the nearby basis.
The current basis rally is supported by tangible supply reductions, limited arrivals and tight tradable inventories. These factors could sustain near-term strength even as the market anticipates a December inventory build.
Nevertheless, the medium-term outlook remains unchanged: new capacity and returning plants are expected to increase supply and rebuild inventories. The key uncertainty is timing. For now, the market remains focused on immediate physical tightness rather than future supply growth.