

Nylon 6 dull FDY 20D/24F: emerging demand recovery |
|
| Irma Zhang | |
| Insight | Time: Nov 5 2026 4:47PM | |
Key takeaways
- Nylon filament price gains stem chiefly from surging CPL costs and tight supply, not solid end-user demand recovery.
- CPL operating rates will drop in early September on unit outages and delayed restarts, sustaining near-term raw material tightness.
- Downstream fabric mills practice hand-to-mouth buying and minimal bulk stocking amid weak finished-goods orders.
- The "Golden September & Silver October" peak may deliver modest demand gains, with robust seasonal performance uncertain.
- Market players should pursue low-inventory, high-frequency buying; heavy speculative stock-building is inadvisable amid cost-demand divergence.
Market overview
After prolonged weakness, demand for dull FDY 20D/24F has picked up recently. This shift is mainly driven by higher fabric scheduling for nylon taffta 380T at downstream fabric mills. Supported by this demand, dull FDY 20D/24F prices have stayed steady, and processing spreads have recovered from prior lows.
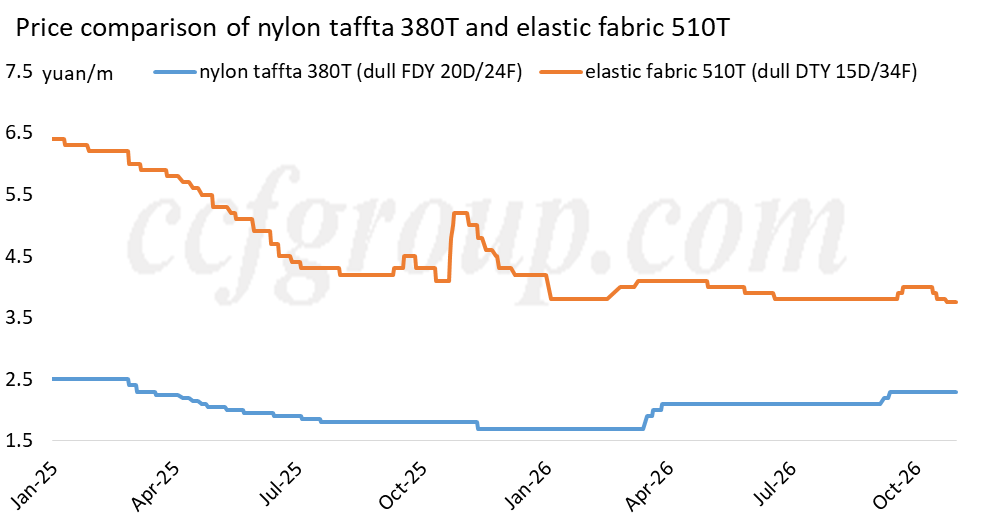
Nylon taffta 380T fabric prices have trended higher this year. Prices climbed from 1.7yuan/m at the start of the year to 2.3yuan/m currently, marking a 35% gain.
By contrast, 510T nylon stretch fabric has traded within a range of 3.8-4.1yuan/m this year. It rose 0.2yuan/m in September alongside raw material costs, yet quickly fell back to 3.8yuan/m or lower in October, returning to early-year levels.
These two fabrics run on the same type of weaving machines. Amid the same market environment, nylon taffta 380T demonstrates stronger price performance than elastic fabric 510T.
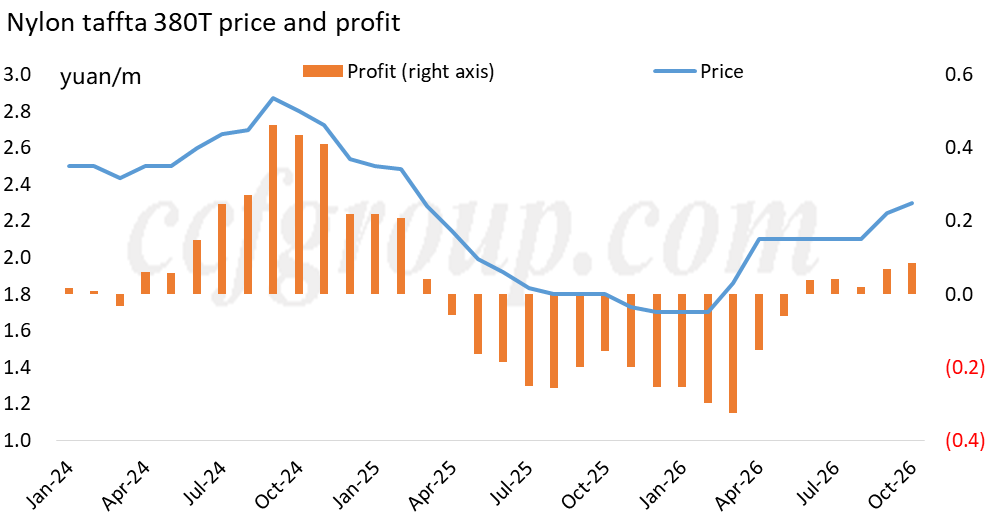
The firm price performance of nylon taffta 380T comes from a tight supply-demand balance after substantial supply cuts.
Nylon taffta 380T saw oversupply last year. Prices kept falling and margins shrank into consistent losses. Even mills in northern Jiangsu with relatively low production costs operated at a loss on a spot buy-and-produce basis through the whole year.
Many fabric mills gradually switched production to profitable elastic fabric 510T, which reduced nylon taffta 380T output. As social inventory of nylon taffta 380T kept falling, its supply-demand structure improved. The fabric could follow raw material price increases smoothly, and processing spreads turned positive.
elastic fabric 510T is not yet loss-making at current prices, but new supply has grown excessively. Some fabric mills carry inventories equal to 3 months of output or more. Inventory drawdown was limited even in the October peak season.
To mitigate inventory build-up for 510T, mills are shifting some looms toward nylon taffta 380T. This is a rational choice given low inventory and restored profitability for nylon taffta 380T. Such capacity switching has become noticeable recently.
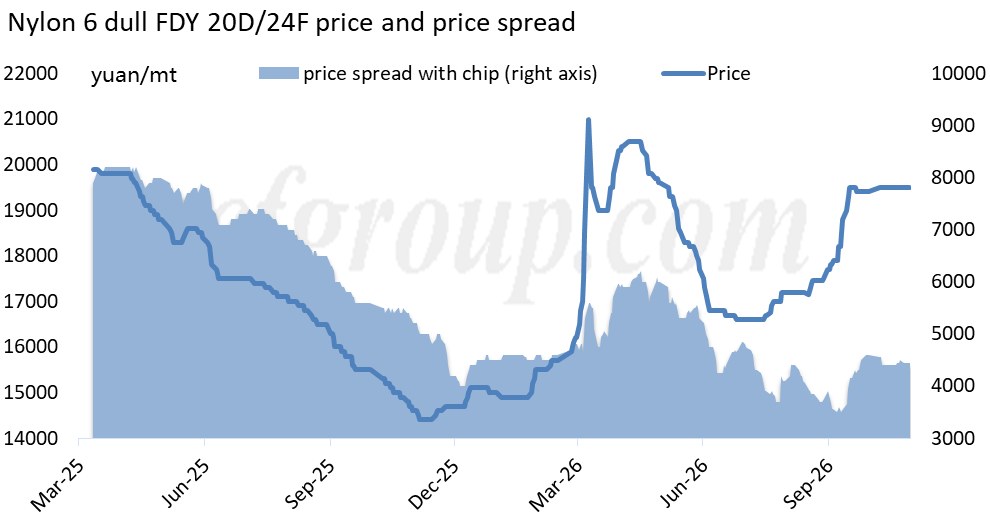
Output of nylon taffta 380T dropped notably in the first three quarters, which dragged down consumption of dull FDY 20D/24F. Intense competition pushed dull FDY 20D/24F processing spreads down to near 3,500yuan/mt.
Facing sustained losses, major dull FDY 20D/24F producers reduced output, and social inventory declined accordingly.
Recently, higher fabric production of nylon taffta 380T lifted dull FDY 20D/24F demand. Some yarn mills hold firm offers amid tight supply. Main transaction prices have recovered to 19,500yuan/mt or above, while premium grades trade above 20,000yuan/mt, with processing spreads partially repaired.
Meanwhile, reduced 510T production lowers consumption of DTY 15/34. DTY prices face downward pressure, falling from 35,000-36,000yuan/mt previously to around 34,000yuan/mt.
Fabric mills switch to nylon taffta 380T not because of strong end-user demand growth. The shift is driven by the tight supply-demand balance and improved processing spreads after prolonged output cuts. At the same time, high inventory of previously abundant elastic fabric 510T calls for output control.
New supply of nylon taffta 380T will soon fill the current supply gap. Its market will gradually shift from tight balance to balanced, then to oversupply. Once inventory rises, the current dull FDY 20D/24F demand momentum will fade. The positive trend may only persist for around one month before conditions change.