
• Home
    • News Insight Snapshot Morning express Daily Weekly Operation report Monthly
    • Market price Database Annual report Researchpremium Focuspremium Mobile Apppremium      
  • Data & API Services
  • Consulting
  • Industry Conference
  • Company Profile Contact Us Website Guide
  • FAQ
  •     
7-day free trial Login
  • Chemicals
    Benzene Styrene Toluene Xylene Methanol DEG PP PE
  • Polyester
    PX/PTA MEG PET fiber chip PET bottle chip PFY PSF
  • Recycled fiber
    PET Flakes Re-PSF Re-PFY
  • Nylon
    CPL/PA6 AA/PA66 Nylon Fiber
  • Spandex
    PTMEG/MDI Spandex
  • Acrylic
    Acrylonitrile Acrylic Fiber
  • Cellulose
    Cotton linter/refined cotton Pulp VSF VFY Rayon yarn
  • Cotton
  • Spun Yarn
  • Textiles
  • Researchpremium
  • Focuspremium
×

Polyester: High cost pressure finally transmitted to filament yarn

Tina Kong
Insight  |  Time: Sep 18 2026 11:11AM
*High polymerization costs in late-July and early-September mainly drove operating rate cuts in staple fiber, bottle chip and chip.
*Entering late September, the PFY segment may gradually begin operation rate cuts or shutdowns.

Dual strait blockades drive crude premium; polyester costs hit new yearly highs

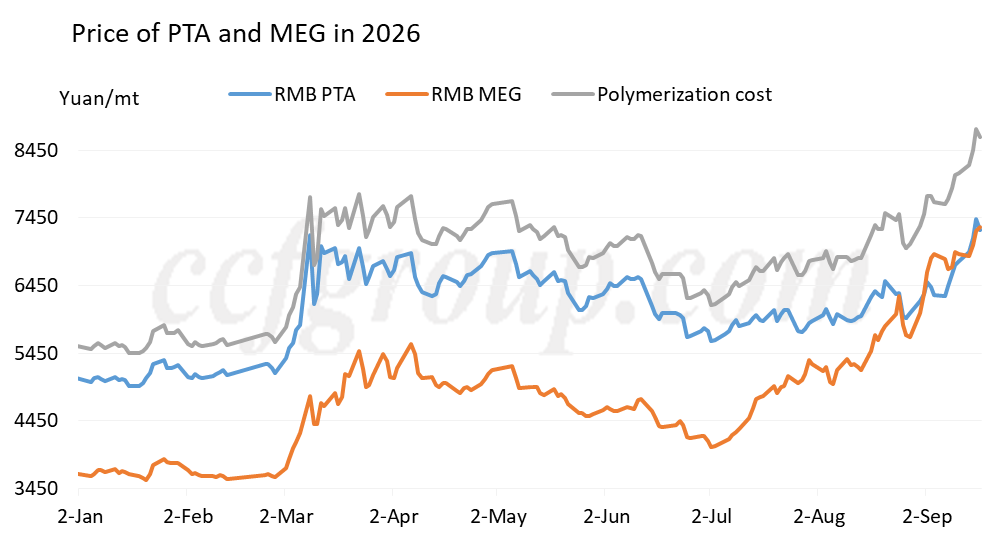
Since mid-July, the Strait has faced a dual blockade, with geopolitical factors driving a higher premium on crude oil. WTI futures broke above US$ 100/barrel, while Dubai (Singapore) crude approached US$130/barrel.


Naphtha-PX-PTA and MEG products enjoyed relatively sound supply-demand fundamentals. Low inventories and circulating stock levels strengthened their processing spread and basis, pushing polyester costs to new yearly highs.


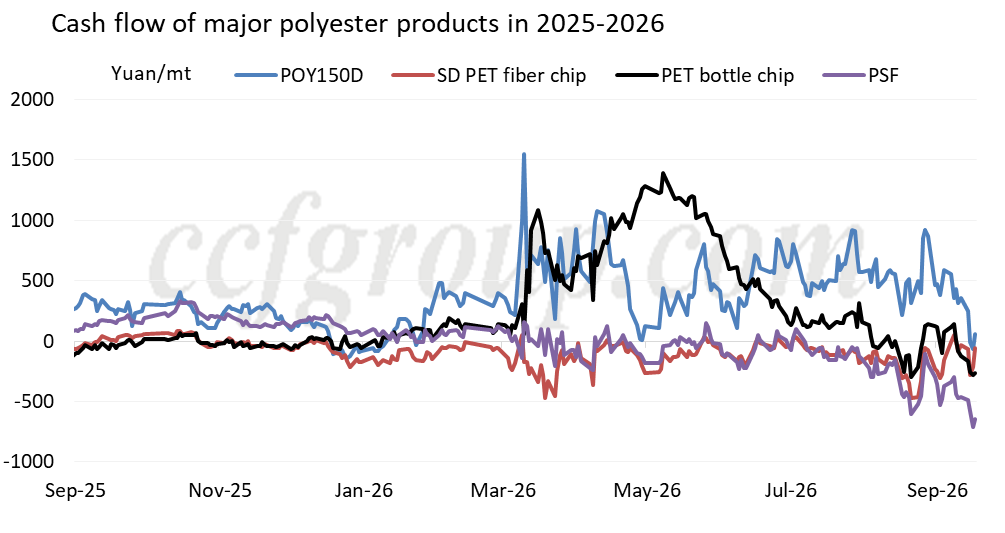
Mainstream polyester products enter across-the-board loss territory

Cash flow losses of the polyester products have extended from staple fiber, PET fiber chip, and PET bottle chip to filament yarn, with mainstream polyester products entering across-the-board loss territory.
Dual-axis line chart tracking PTA spot basis, MEG spot basis and polyester polymerization rate from 2022 to 2026, PTA & MEG basis in Yuan per metric ton, polyester polymerization rate in percentage, polyester raw material supply chain market analysis


Line chart showing cash flow of major polyester products from 2025 to 2026, tracking POY150D, SD PET fiber chip, PET bottle chip and PSF cash flow trends, unit Yuan per metric ton, polyester industry profit analysis


Persistent losses at filament downstream weigh on seasonal orders

Losses at the DTY and fabric markets persist, with weak follow-through on high prices, affecting the volume and pace of seasonal order placement.


As of now, the operating rate of DTY plants in Zhejiang and Jiangsu has declined to 58%: below 80% in Xiaoshan and Shaoxing, 50-60% in Changxing, around 60% in Changshu, near 50% in Taicang, and around 50% in Cixi. The operating rate of fabric mills in Zhejiang and Jiangsu has declined to 59%: water-jet looms at 50-60% in Wujiang, 50-60% in Changxing, and below 60% in North Jiangsu; warp knitting mills at around 90% in Haining and above 50% in Changshu; circular knitting mills at above 40% in Xiaoshan and Shaoxing and around 40% in Changshu.
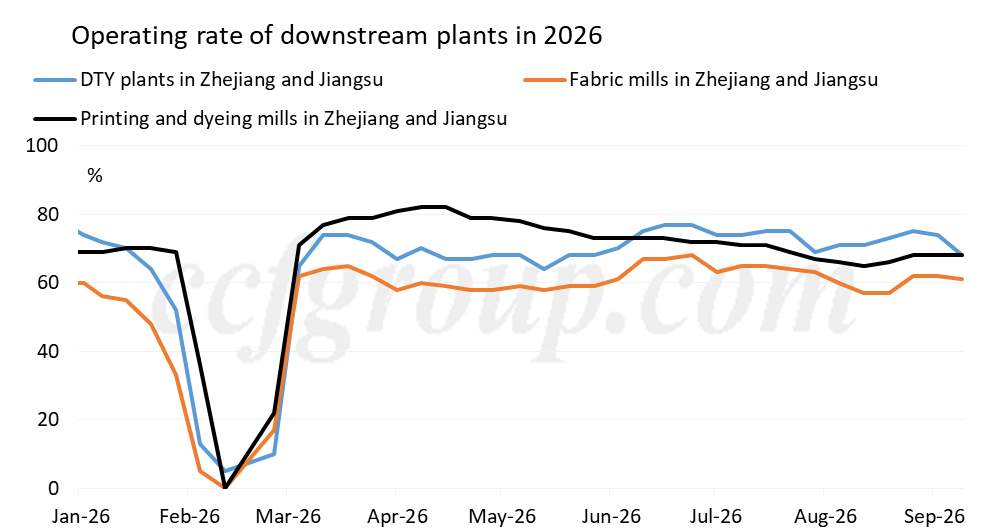

Line chart showing operating rate of downstream textile plants in 2026, tracking DTY plants, fabric mills and printing & dyeing mills in Zhejiang and Jiangsu, capacity utilization percentage trend, polyester downstream market analysis

DTY operating rate down sharply; Production cuts may widen during Mid-Autumn and National Day holidays

Overall, the previous high for DTY plants and fabric mills operating rate was 75% and 62%, respectively, now down 17% and 3%. The notable decline was in DTY, which sits between upstream and downstream, making the pressure from weak processing spread follow-through more pronounced. DTY-related feedstock costs have risen only modestly, providing some cost buffer. However, if the reality of high prices and extremely low processing spread cannot be reversed around the Mid-Autumn Festival, DTY and weaving production cuts will widen further during the Mid-Autumn and National Day period, with some regional customers indicating rates may drop to just 20-30%.


PFY segment may gradually begin run rate cuts or shutdowns

High polymerization costs in late-July and early-September mainly drove operating rate cuts in staple fiber, bottle chip and chip. But entering late September, the PFY segment may gradually begin operation rate cuts or shutdowns, with intentions already emerging at some plants in Fujian, and Ningbo and Xiaoshan/Shaoxing from Zhejiang. Although the reality of low PFY inventories remains unchanged, nominal cash flow has been substantially compressed, with losses at certain points in time, and downstream is also cutting run rate. Some major PFY producers plan to reduce their inventories during September–November, while some PFY plants also face cost pressure from feedstock post-pricing.

Q4 polyester polymerization rate may fall short of expectations, potentially below 70%

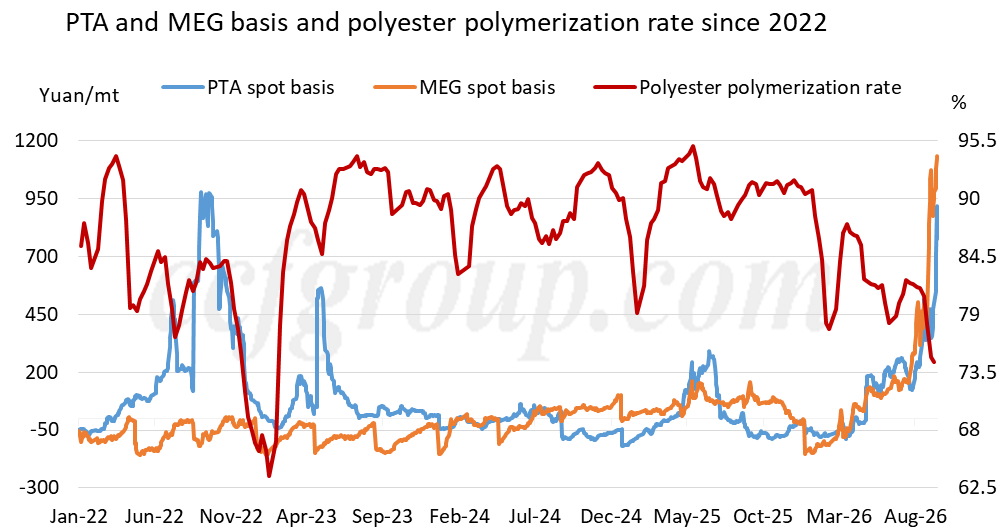
Dual-axis line chart showing PTA spot basis, MEG spot basis and polyester polymerization rate from 2022 to 2026. PTA and MEG basis in Yuan per metric ton, polyester polymerization rate in percentage, polyester raw material supply chain market trend analysis

With the tight supply-demand situation in either PTA or MEG unchanged, the overall polyester polymerization rate in Q4 is estimated to fall short of earlier market expectations, likely ranging between 70-75%, with the possibility of dipping below 70% at the extreme.


[RISK DISCLAIMER] All opinions, news, analysis, prices or other information contained on this report is provided by analyst of Zhejiang Huarui Information Consulting Co., Ltd (CCFGroup) as general market commentary and does not constitute investment advice. CCFGroup will not accept liability for any loss or damage, including without limitation to, any loss of profit, which may arise directly or indirectly from use of or reliance on such information.

Related Articles

    PET bottle chip market morning express (Nov 20, 2026)
    PET bottle chip producers mostly raised offers this morning
    PET fiber chip market morning express (Nov 20, 2026)
    Failure points in apparel performance testing and improvement potential at the material level
    Solid re-PSF offers keep steady in Wujiang
    HC re-PSF offers keep steady

Researchpremium

    Substitution dynamics between virgin and recycled cotton-type PSF
    Operating performance of listed Chinese textile and apparel enterprises in H1 2026
    2025/26 Chinese cotton market fundamental analysis and outlook
    Operation analysis of China's lyocell and rayon printed & dyed fabrics
    Cotton yarn market: H1 review and H2 outlook
    Analysis of polyester demand in H1 2026 and H2 outlook
  • Address
    Huarui Center No. 1027 Jianshe 1st Road,
    Hangzhou, Zhejiang Province, China
  • Phone
    +86-571-8378 6653    +86-571-8378 6504
  • Email
    market@ccfgroup.com
Our Service
  • Home
  • Market price
  • Database
  • Research
  • Focus
  • Website Guide
  • Data & API services
  • Consulting
  • Industry conference
  • Company profile
  • Mobile app
  • FAQ
About Us


A leading provider of market intelligence, data services, and industry insights across the petrochemical, chemical fiber, and textile value chains.

© Huarui Information All Rights Reserved   Privacy Policy · Terms of Use

China ICP License: 浙B2-20110322-3
浙公网安备33010902000742号