

LDPE price surge drives EVA-to-LDPE switching |
|
| Amber | |
| Insight | Time: Sep 10 2026 4:28PM | |
Starting in late August, China's domestic PE market staged a strong rally, with LDPE showing particularly robust performance. Taking the East China price index as an example, the East China LDPE price index stood at 10,750yuan/mt on August 28, then jumped to around 11,800yuan/mt by September 4, a gain of nearly 10%.
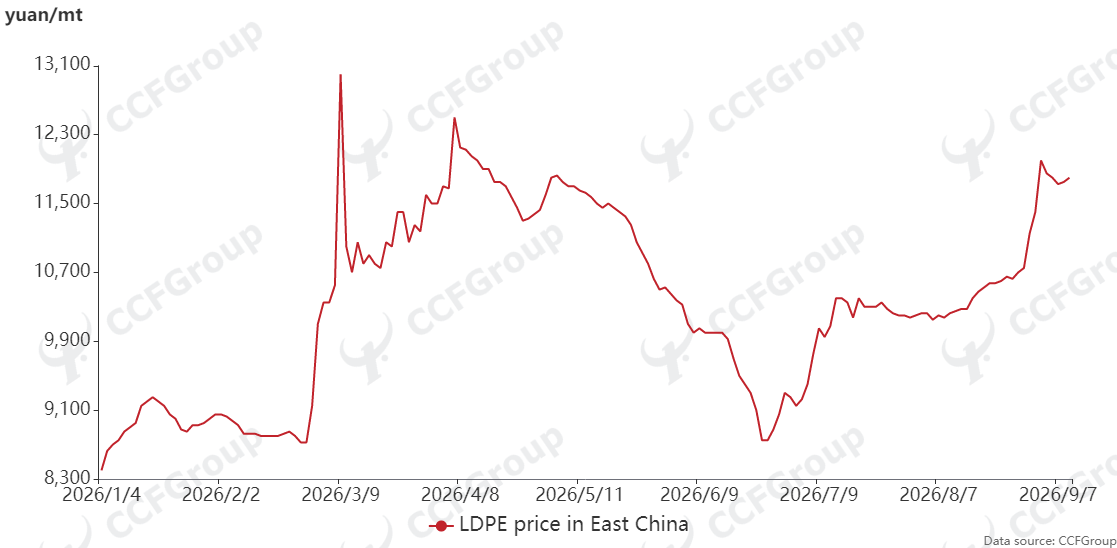
Behind this sharp rise in LDPE prices, multiple factors have converged. In late August, Middle East conflicts flared up again, and overnight crude oil prices rose sharply, strongly driving the overall PE market trend. Furthermore, after entering September, seasonal demand from some LDPE downstream sectors picked up, providing modest support to the market, while at that time China's overall LDPE supply was relatively low. Together, these factors pushed prices up strongly.
LDPE's strong performance has further widened the price spread between LDPE and EVA. Looking back at the downturn in May 2026, EVA prices fell sharply, with declines significantly exceeding those of LDPE, turning the spread between the two from negative to positive. After entering July, LDPE began a choppy rebound, while EVA did not follow suit, lingering in a low range for an extended period. Only recently has EVA shown a slight recovery, but the gain is far smaller than LDPE's. According to market sources, last week mainstream EVA prices were around 10,000-10,500yuan/mt, while LDPE prices over the same period reached around 11,500-12,000 yuan/mt, widening the spread to around 1,500 yuan/mt.
Against the backdrop of LDPE's strong upward trend and the ever-widening spread with EVA, petrochemical plants, aiming to maximize profits, have adjusted their production schedules, switching some units originally producing EVA to LDPE production, and the market supply structure has shifted noticeably as a result.
Taken together, the LDPE production share of China's domestic PE units has now risen to 10.02% (excluding Sinochem Quanzhou for the time being).
Looking ahead, the LDPE market's supply-demand landscape is facing new changes. On the supply side, from September to December, China's LDPE market is expected to show an overall pattern of ample supply and gradually recovering demand. In addition to the above-mentioned EVA unit switches, some new plants are expected to start up in Q4, and overseas cargo arrivals are expected to recover steadily, potentially significantly expanding spot supply. On the demand side, greenhouse film demand gradually kicks off from late August to September, with downstream factories needing to stock up. Even after agricultural film demand winds down later, e-commerce shopping festivals and year-end packaging demand will gradually follow, leaving room for phased demand recovery.
However, precisely because the supply increase from unit switches and new capacity will be gradually released, supply pressure on the LDPE market will progressively intensify. With no demand-side surge exceeding expectations, the risk of a high-level pullback in LDPE prices has further increased after this strong rally. Going forward, close attention should be paid to the pace of new unit commissioning, the continued guidance of EVA/LDPE spread changes on unit switching behavior, and the arrival of imported cargoes.