

How long will cotton linter price rally last before new crop arrives? |
|
| Monica Jiang | |
| Insight | Time: Aug 18 2026 10:32AM | |
Recently, boll opening of new cotton has accelerated in inland China and Xinjiang. Sporadic volumes of new seed cotton have come onto the market in inland regions. It is expected that hand-picked seed cotton output will gradually increase from late Aug to early Sep. New-season cottonseed is yet to be available, with prices remaining stable overall. Cotton linter prices have surged since the end of Jul and beginning of Aug.
Sporadic volumes of new seed cotton have appeared in inland areas recently, with scattered purchasing activities underway in parts of Shandong and Hebei. Current seed cotton purchase prices stand at around 7.4-7.6yuan/kg in Shandong and Hebei. Given limited supply, ginners have not officially opened purchase scales, and no unified procurement price has been formed. Harvest volumes are projected to rise gradually in Shandong, Hebei and Hubei by the end of Aug, while seed cotton harvesting in Xinjiang will officially commence in early to mid-Sep.
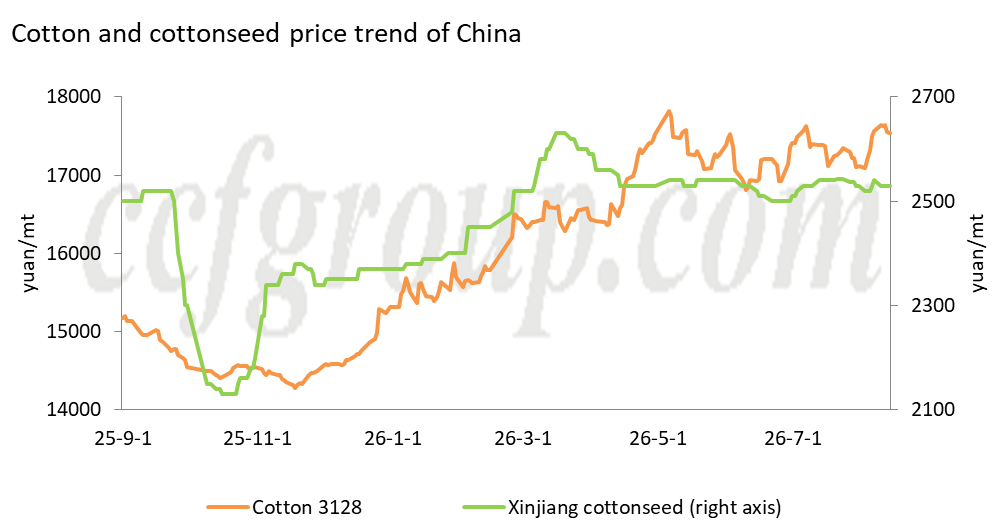
New cottonseed has not yet entered the market, and the market is in a transition period between old and new supplies. Stocks of old cottonseed continue to be depleted, and high-quality supplies are scarce. After a gradual decline in prices earlier, quotations have stabilized recently without notable fluctuations. Current cottonseed prices in Xinjiang are mostly around 2,470-2,520yuan/mt. Following the successive arrival of new cottonseed supplies after mid-Sep, cottonseed prices will fluctuate in H2 of the year, likely trading within the range of 2,250-2,550yuan/mt.
El Nino this year has intensified extreme weather across global cotton-producing regions. Xinjiang suffered persistent high temperatures and drought in Jul and Aug over an extensive area with severe intensity. Average temperatures across Xinjiang's cotton belts have been higher than seasonal averages recently. Heatwaves in some areas of Xinjiang have caused boll drop at the top of cotton plants, with relatively high shedding rates of squares and bolls in some cotton-growing zones, stoking expectations of lower cotton yields. Coupled with mounting market expectations for the textile industry's traditional peak demand season "Golden September & Silver October", seed cotton purchase prices are likely to open higher this year. ZCE cotton futures and spot cotton prices still retain upward momentum.
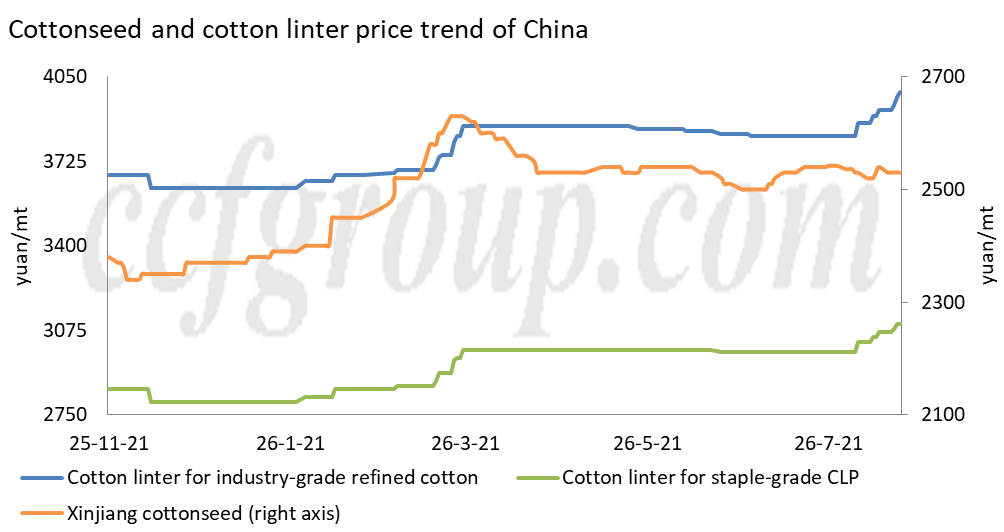
Towards the end of 2025/26 crop year, cotton linter market is experiencing a supply gap. Inventories of old linters are being consumed continuously, while new linters are still far from market availability. In addition, cotton linter imports in H1 of this year plunged more than 62% year-on-year, easing overall supply pressure. Suppliers have shown strong willingness to uphold prices recently. Cotton linter prices have risen by about 200-300yuan/mt since the end of Jul. At present, cotton linter for industry-grade refined cotton in Xinjiang is priced near 3,600-3,700yuan/mt, and around 4,000yuan/mt in inland areas. Many cottonseed oil mills and delinting plants plan to resume production after the National Day holiday. Prices are expected to remain firm before large volumes of new linters hit the market.
In summary, boll opening of new cotton has accelerated in inland China and Xinjiang, and sporadic new seed cotton has arrived in inland markets. Ginners are still adopting a wait-and-see stance pending the official launch of purchasing. Harvest volumes will gradually increase in Shandong, Hebei and Hubei by the end of Aug, and seed cotton harvesting in Xinjiang will officially kick off in early to mid-Sep.
New cottonseed is still unavailable amid the transition from old to new supplies, and prices stay stable temporarily. After mid-Sep, as new cottonseed comes onto the market continuously, especially with accelerated machine-picked seed cotton around the National Day holiday, new cottonseed supply will expand and prices will face downward pressure. Prices are forecast to fluctuate within the range of 2,250-2,550yuan/mt in H2 of the year. Cotton planting areas have declined markedly this year. Exacerbated by El Nino-triggered extreme weather worldwide, expectations of lower yields have strengthened. Cotton linter market is currently caught in a supply gap, and cotton linter prices have climbed rapidly since the end of Jul. Prices are anticipated to stay firm before mass arrivals of new linters.