

China methanol price consolidates, awaiting Middle East conflict resolution |
|
| Louis | |
| Insight | Time: May 27 2026 2:26PM | |
Total methanol shipment arrivals in China in May are projected to be around 330,000 to 340,000 tons, a decrease of 220,000 tons from April. The decrease is mainly due to the shortfall in Iranian cargoes (loaded in April and arriving in China in May) of about 150,000 tons compared to the previous month.
Looking forward to June, although there is still no clear news on whether the Strait of Hormuz will open, controls over the Strait have slightly loosened. As of May 26, a month-to-date 165,000 tons of Iranian cargoes have already passed through the Strait, with another vessel currently in transit.
Iranian cargo loaded in May is expected to be around 205,000 tons. As a result, China's methanol imports for June (arriving in China in June) is projected to increase compared with May, potentially reaching around 500,000 tons.
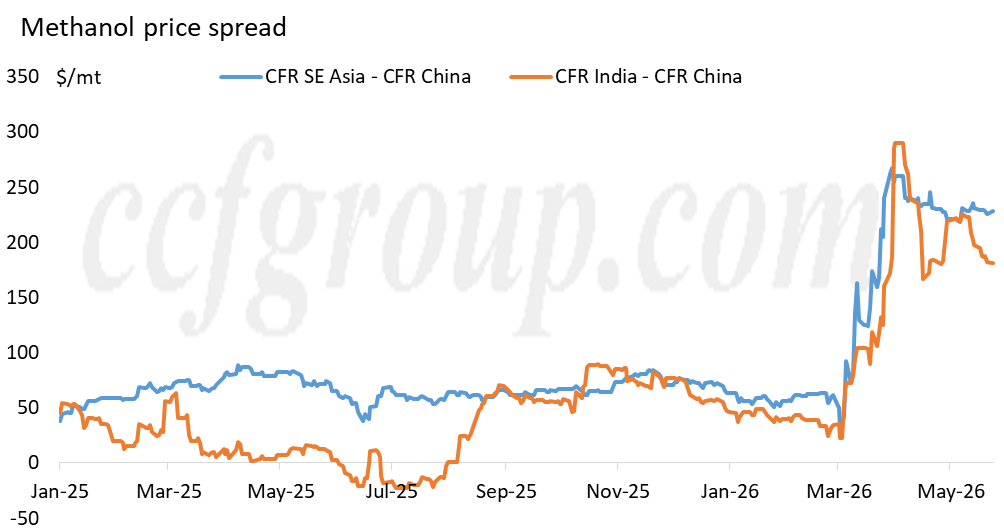
As for exports, China's methanol export volume in April was 173,000 tons, and it is projected to be around 150,000 tons in May. Recently, the India-China price spread has narrowed slightly but remains relatively large, while the Southeast Asia-China price spread has generally held steady.
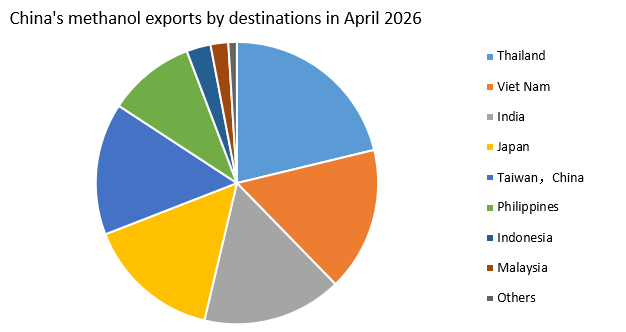
In terms of export destinations for Chinese methanol in April, Thailand, Vietnam, and India were the top three. The export pattern in May is expected to continue, with India, Southeast Asia, and East Asia remaining the main destinations.
Tank inventories of methanol at Chinese ports are at historical lows, keeping supply tight. Despite strong market expectations for Iranian methanol unit restarts, the key uncertainty remains shipping through the Strait of Hormuz. With no reopening timeline, recovery of Iranian supply is uncertain.
Consequently, port inventories lack replenishment sources. Although some shutdown of MTO plant in coastal China has slowed methanol destocking, inventories are likely to continue falling to new lows, providing strong support for coastal methanol prices.
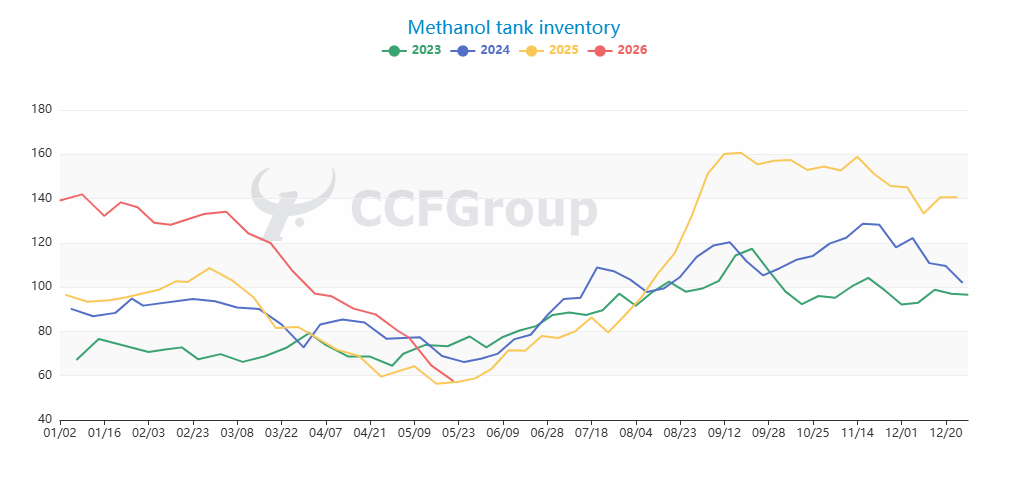
unit: 10,000 tons
China domestic methanol operating rates remain above seasonal averages. Meanwhile, Sierbang's MTO unit plans to shut down and has suspended contracts for methanol supplies from inland China, pressuring methanol price in interior regions.
However, with coastal imports tightening, inland supplies will continue flowing to coastal markets, and domestic methanol plants in inland China can maintain low inventories with no build-up pressure yet.
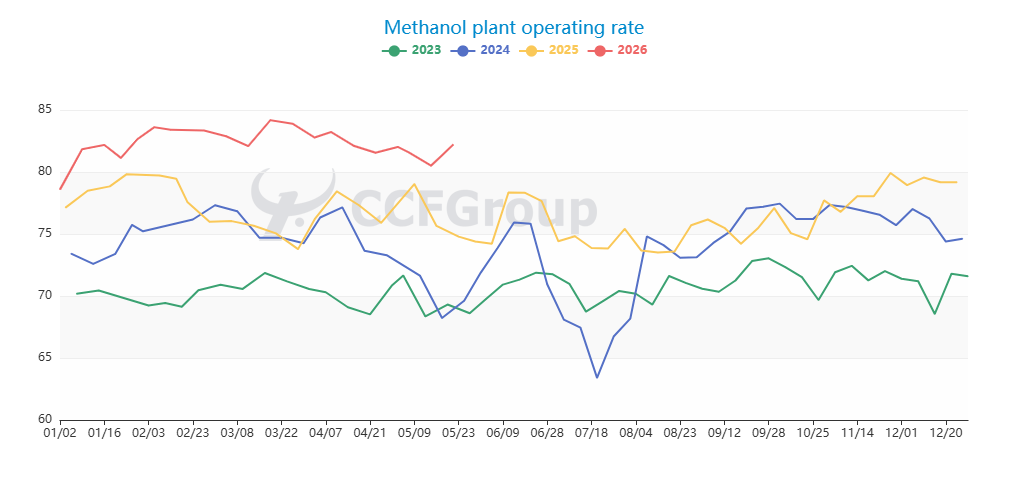
Unit: %
Two coastal MTO plants using merchant methanol have seen operational changes. Ningbo Fund shut its MTO plant on May 26 due to a feedstock methanol supply gap. The next shipment of imported methanol cargo will arrive in early June, so the plant outage will last about ten days.
The other plant, Sierbang, originally scheduled to shut on the 20th, has been cutting operating rate since May 22.
Among traditional downstream sectors, formaldehyde and acetic acid operating rates have edged up from lows, while MTBE operating rate fell on weaker exports. Overall, demand-side negative feedback persists.
In a conclusion, methanol futures decline has priced in both demand weakness and higher import expectations. But the strong reality, reflected in record-low inventories and a solid spot-futures basis, remains.
The market is trapped between strong reality and weak expectations, with no clear direction.